Beyond the Purchase Price: How a 2-1 Mortgage Buydown Can Create Opportunities
When buying a home, most people focus on two numbers: the purchase price and the mortgage interest rate.
But sometimes, the real opportunity isn't simply in the price you negotiate. It's in how you structure the deal.
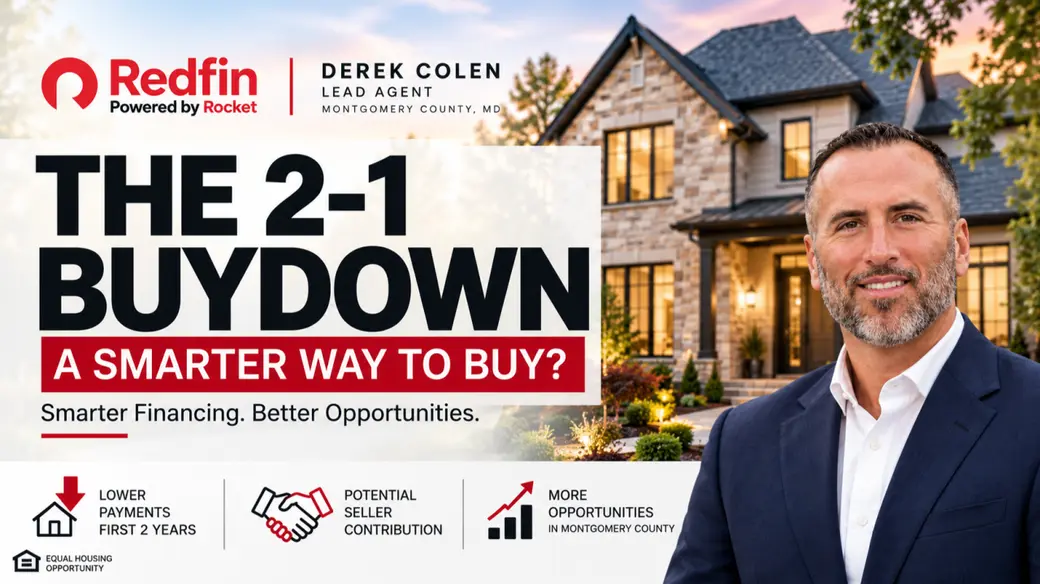
One financing strategy worth understanding is the 2-1 mortgage rate buydown. This approach temporarily reduces a buyer's monthly mortgage payments during the first two years of homeownership. In certain transactions, sellers may even contribute toward the cost.
For buyers and sellers alike, it's another example of how thoughtful financing and negotiation can create opportunities.
What Exactly Is a 2-1 Mortgage Buydown?
A 2-1 buydown is a temporary financing arrangement that reduces a buyer's monthly mortgage payment during the first two years of a fixed-rate loan.
Using a reported national average 30-year fixed mortgage rate of 7.57% as of October 13, 2026, here's how the strategy works.
Consider a $700,000 home purchase with a 20% down payment, resulting in a $560,000 mortgage.
YEAR 1 — 5.57% Payment Rate
Monthly Principal & Interest: $3,204
Approximately $738 per month in payment relief
YEAR 2 — 6.57% Payment Rate
Monthly Principal & Interest: $3,565
Approximately $377 per month in payment relief
YEAR 3 & BEYOND — 7.57% Payment Rate
Monthly Principal & Interest: $3,942
Over $13,000 in Temporary Payment Relief During the First Two Years
The mortgage's actual interest rate remains 7.57% throughout the loan. An upfront-funded subsidy covers the difference between the full mortgage payment and the reduced payments during the first two years.
The payment relief is not free money, nor does it reduce the loan's underlying interest rate. Rather, it provides temporary cash-flow flexibility.
Figures are approximate and reflect principal and interest only. Property taxes, homeowners insurance, HOA fees, and other housing expenses are excluded.
Where Smart Negotiation Creates Opportunities
One of the more interesting aspects of a 2-1 buydown is how it can become part of a real estate negotiation.
In certain situations, a seller may be willing to contribute toward the upfront cost of the buydown.
Rather than focusing exclusively on negotiating a lower purchase price, buyers and sellers can explore financing concessions that may benefit both parties.
For Buyers: Lower initial mortgage payments can provide additional financial flexibility during the first two years of homeownership.
For Sellers: Offering a contribution toward a temporary buydown may help make a property more attractive without necessarily reducing the asking price.
Of course, these strategies depend on the property, financing program, seller concessions, and overall transaction terms.
Sometimes the strongest negotiation isn't simply about price. It's about finding the right combination of price, terms, and financing.
Why Strategy Matters in Montgomery County
One thing I've learned over more than 14 years in residential real estate is that Montgomery County isn't one single housing market.
Market conditions in Bethesda may look very different from those in Rockville, Gaithersburg, Germantown, or Clarksburg.
Some properties attract multiple offers, while others present opportunities to negotiate more favorable terms.
That's why understanding the local market is so important.
For buyers, it means evaluating a property's value, exploring financing options, and recognizing opportunities to negotiate.
For sellers, it means pricing strategically, understanding buyer motivations, and positioning a property to compete effectively.
Every home, every neighborhood, and every transaction deserves its own strategy.
The Bottom Line: Strategy Creates Opportunity
A 2-1 mortgage rate buydown isn't the right fit for every transaction. Buyers must generally qualify based on the full mortgage payment, and the temporary payment reduction requires upfront funding.
It also shouldn't be approached with the assumption that refinancing into a lower rate will necessarily be available in the future.
However, it's another example of how financing strategies and thoughtful negotiation can create opportunities for both buyers and sellers.
In a market where conditions can vary significantly by neighborhood, price point, and property type, understanding the available options is just as important as understanding the numbers.
Real estate success isn't simply about negotiating the lowest price. It's about understanding the market, evaluating the options, and structuring the right deal.
Mortgage rate reference: Bankrate, October 13, 2026. This is an illustrative 30-year fixed-rate mortgage example, not a loan quote or offer of credit. Temporary buydowns require upfront funding and lender approval. Loan eligibility, seller contribution limits, and program requirements vary.
Categories
Recent Posts